Türkiye Payroll & Employment Guide
Turkish payroll brings labour law, social security and income tax into the same monthly cycle. Income tax runs on a cumulative base. Social security contributions are calculated within a lower and an upper contribution base. The two bases can start from the same pay components but they do not follow the same rules. The gross minimum wage is TRY 33,030 in 2026. The upper contribution base has risen to nine times the minimum wage, the employer share of long-term insurance branches has increased by one point, and the general premium reduction outside manufacturing has fallen from four points to two. Employer cost and the value of incentives have therefore changed even where gross pay is unchanged.
- 18
- pages
- 9
- chapters
- 2.237
- words
- TRY
- currency
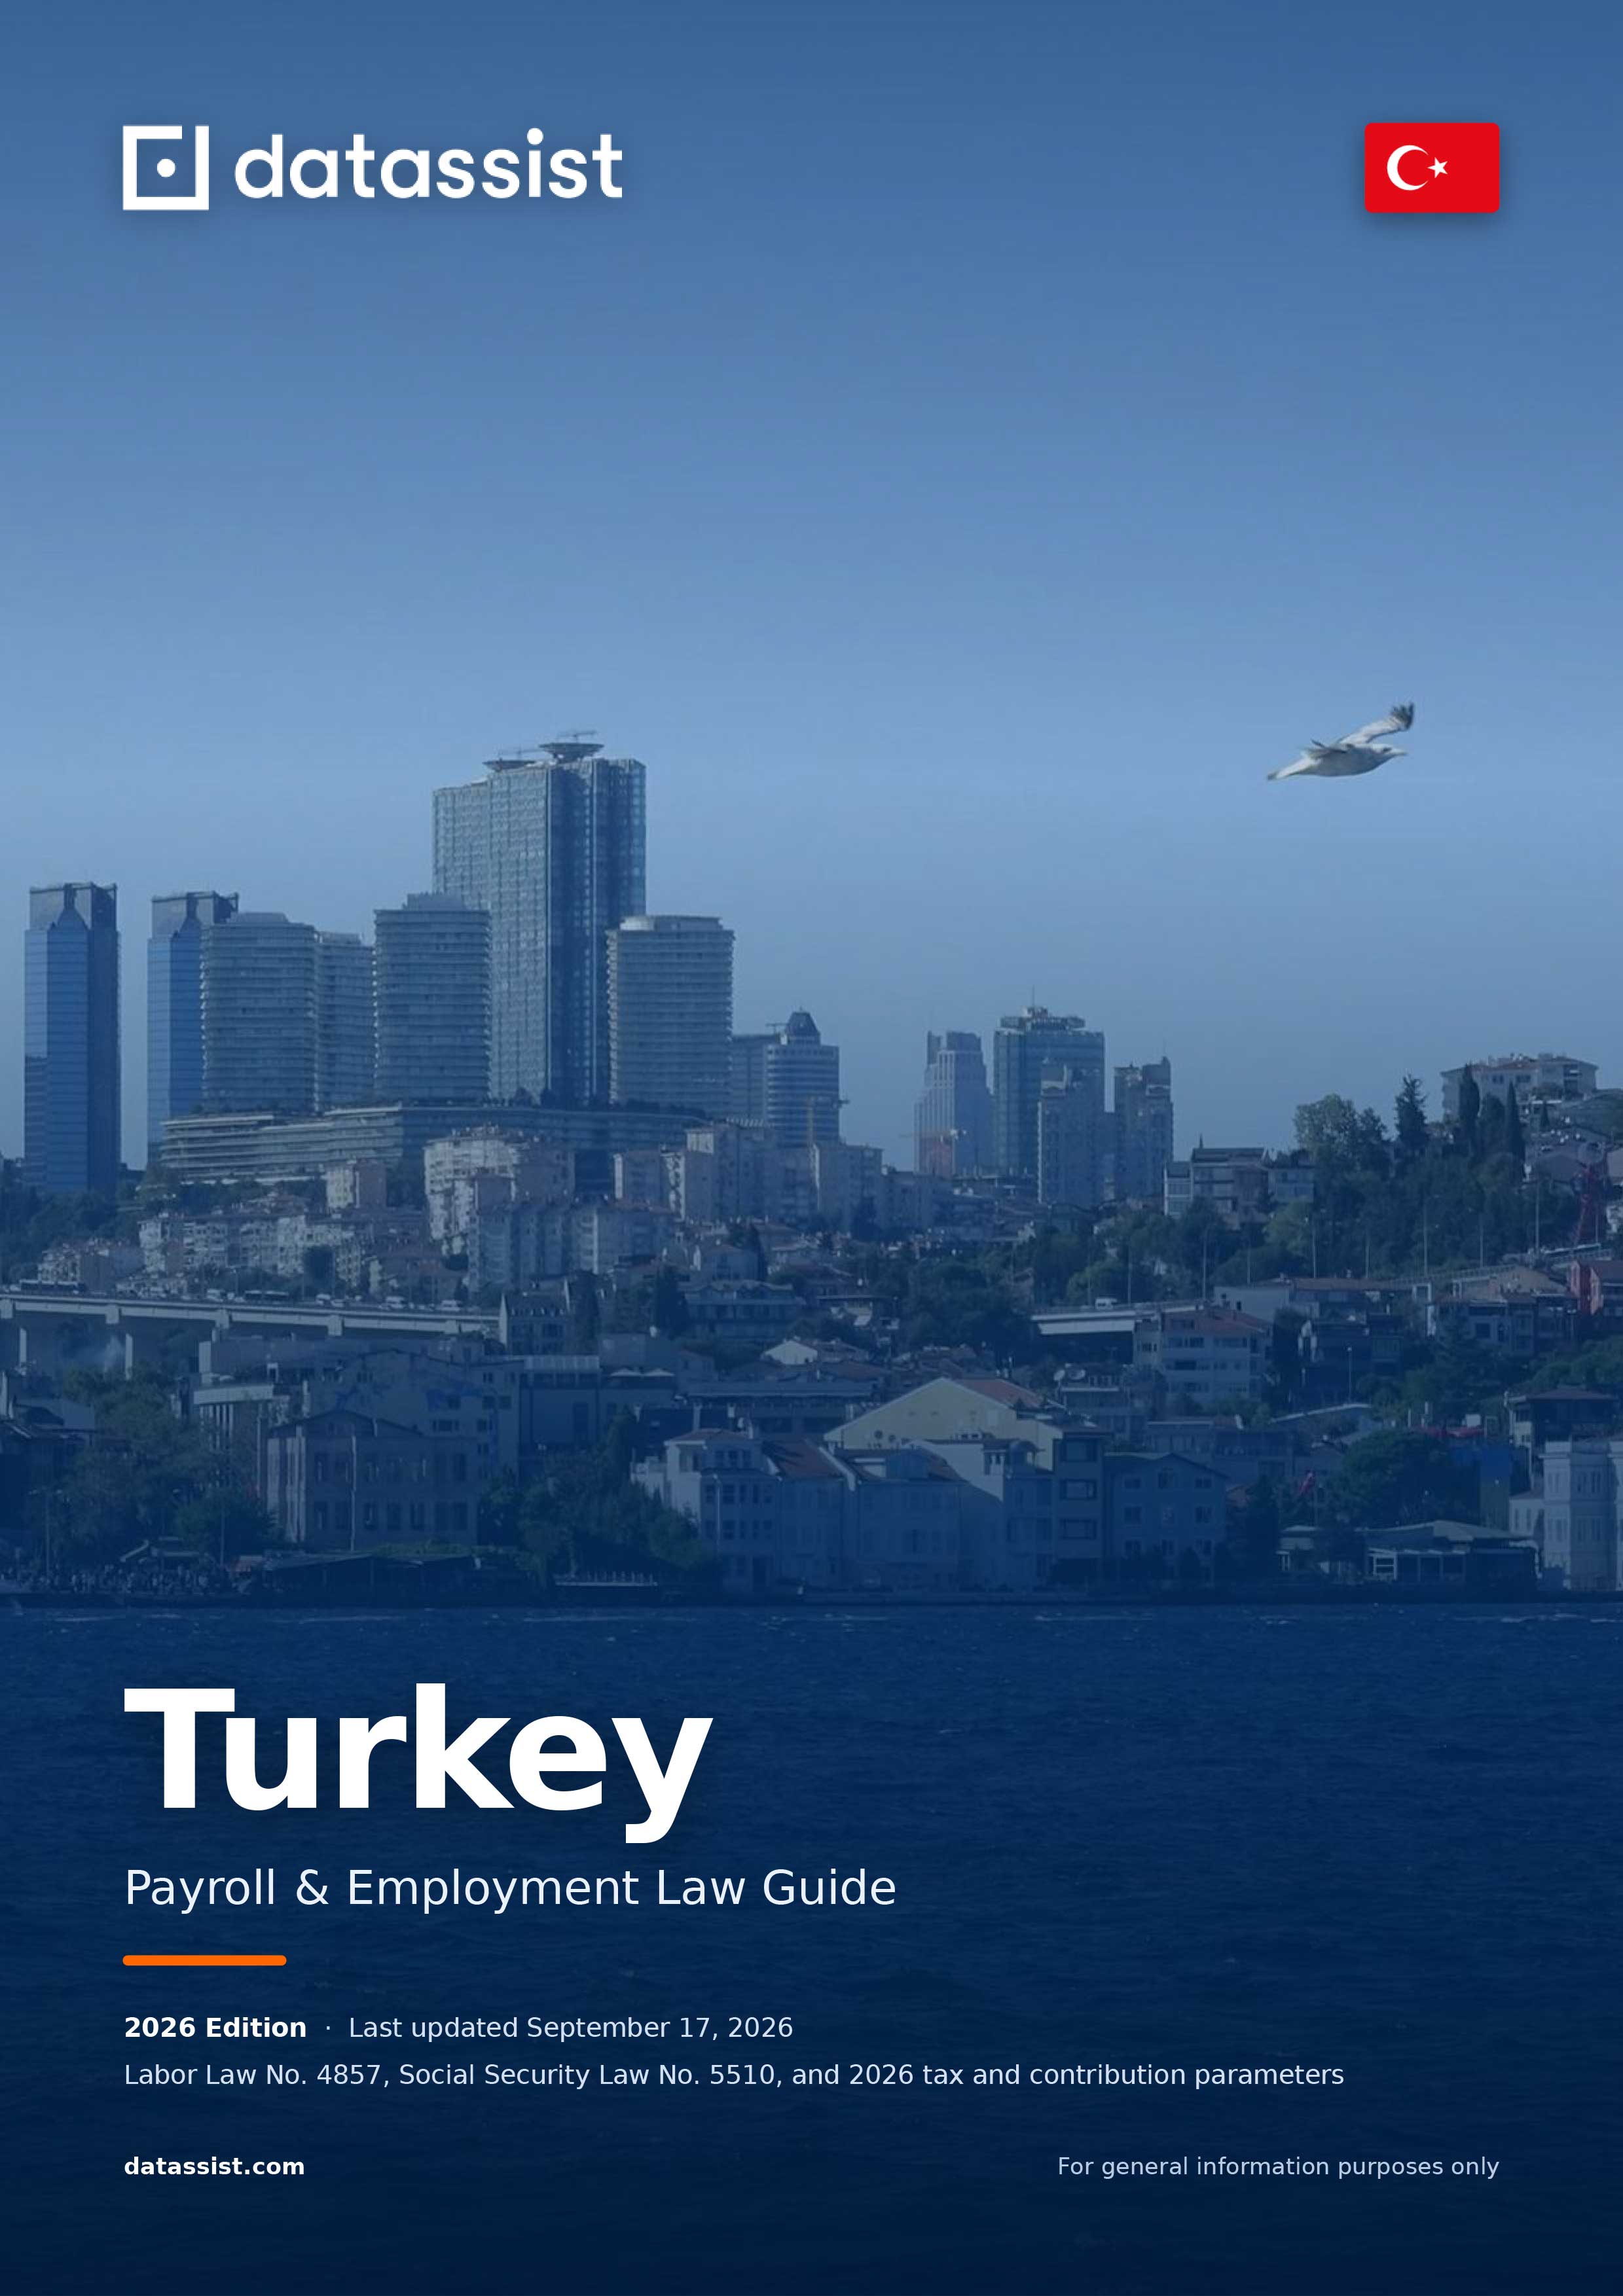
At a glance
Four key payroll indicators for Türkiye
- TRY 33,030
- 2026 monthly gross minimum wage
- 45 hours maximum
- Normal weekly working time
- 38.75%, employer 23.75% and employee 15%
- Total social security rate
- TRY 297,270
- Upper contribution base ceiling
What's in the guide
9 chapters, 18 pages
The opening summary of each chapter is below. Full text, tables and rates are in the PDF.
Employer Structure & Contract
Company types, employer registration and the limits of temporary employment.
Employment in Türkiye starts on a legal footing created at incorporation. Company type, trade registry entry, tax registration and social security workplace registration follow one another but create separate obligations. The workplace declaration and employer user definitions must be completed before any employee is hired.
Working Time & Leave
Weekly hours, overtime premiums, annual leave and maternity rights.
Working time, overtime and leave form the time data behind the payroll calculation. Missing days, overtime, weekly rest and paid leave records must stay consistent with the payslip.
Tax & Social Security
2026 minimum wage, contribution rates and the income tax schedule.
The lower contribution base equals the gross minimum wage in 2026. The upper base is nine times the minimum wage. Even where gross pay exceeds the ceiling, contributions are calculated on no more than TRY 297,270.
Payroll Operations
Monthly calendar, filing deadlines and the bank payment requirement.
Payroll is not limited to the net pay calculation. Time records, benefits, tax exemptions, social security reporting, tax filing, bank payment and accounting entries must be reconciled for the same period.
Hiring & Termination
Social security notifications, notice periods and severance pay.
Onboarding and offboarding carry the highest deadline and documentation risk in payroll. Contract type, social security notification, termination grounds, notice period and final settlement need to be supported in the same file.
Pay & Benefits
Employer cost, bonuses and payroll treatment of benefits.
Not every element of the pay package is processed the same way in payroll. Cash payments, benefits in kind, expense reimbursements, bonuses and private insurance payments each require a separate tax and social security assessment.
Work Permits & Foreign Employment
Permit terms and the 2026 assessment thresholds.
An employment contract alone does not give a foreign national the right to work. The permit process under International Labour Force Law No. 6735 creates separate information and documentation obligations for the employer and the foreign national. A residence permit alone does not confer a right to work.
Practical Checklist
Items to complete before the first payroll.
Are the employment contract and pay components recorded in writing? Are time, leave and sickness records closed at period end? Have the social security base and the income tax base been checked separately?
Incentives & Employer Support
Social security premium incentives in force in 2026 and their conditions.
Fourteen social security premium incentives are in force in Türkiye as at 2026. Thirteen apply to private sector workplaces employing insured persons under Article 4/1-a and one applies to insured persons under Article 4/1-b. Incentives are claimed through the monthly premium declaration under a law document number. They are not a separate grant payment.
This guide is for general information only; it is not legal advice or a complete statement of the law. The content reflects the legislation in force when it was prepared, and legislation changes. Always take country-specific professional advice on a concrete case.
With Datassist
Managing Türkiye Payroll with Datassist
Datassist helps you run Turkish payroll in a single operating framework that covers labour law, social security, income tax and incentive checks. Payroll inputs are validated before calculation, and monthly filings, premium payments and incentive eligibility are tracked through reconciliation.
Other countries
Other country guides
- 10 hours
- Daily ceiling with averaging
- EUR 12,348
- 2026 annual income tax allowance
Employer Structure · Working Time & Leave · Tax & Social Security · Payroll Operations
View Guide
- EUR 14.99
- Gross hourly minimum wage for age 21 and over
- 160 hours
- Statutory annual leave for a 40-hour week
Employer Structure · Working Time & Leave · Tax & Social Security · Payroll Operations
View Guide
- 40 hours
- Standard working week
- 4 weeks
- Minimum paid annual leave
Employer Structure · Working Time & Leave · Tax & Social Security · Payroll Operations
View Guide